By George Brown, Senior US Economist at Schroders
Is AI replacing workers at scale? The market, the Federal Reserve and commentators far and wide appear to believe that AI is already displacing jobs, setting the scene for further disinflation and rate cuts. Incoming evidence suggests this could be a false narrative. AI may well create slack in the future, but cutting rates now on the hopes of new technology – and especially in the light of events in Iran and the Middle East – would seem more like wishful thinking than prudent policymaking.
In the period since ChatGPT’s launch the share of job advertisements mentioning AI related skills has climbed steadily, according to recruitment site Indeed.com. But correlation alone does not tell us whether AI is truly weighing on job creation. There are other significant factors at play. To start with…
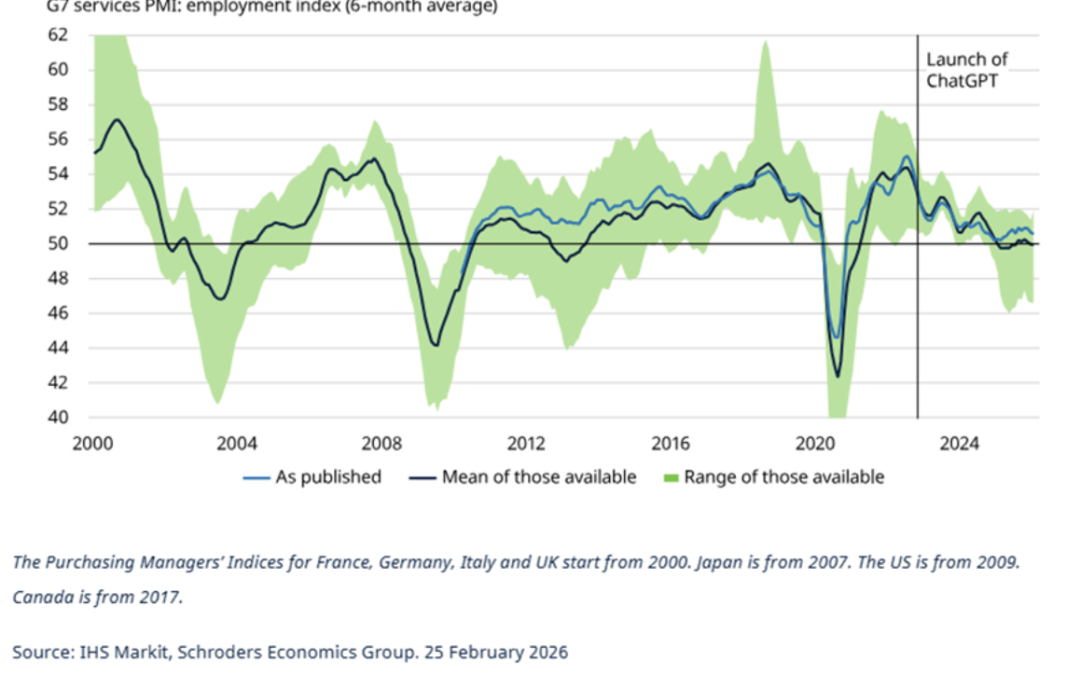
Labour conditions have softened globally since late 2022
If AI were displacing workers meaningfully, there ought to be a clear improvement in labour productivity. Yet outside the US, there has been no discernible acceleration, suggesting that AI’s impact on G6 job markets has been limited so far.
However, we can’t rule this out for the US economy, given its productivity performance (see top line in the chart below).
G6 productivity is inconsistent with AI displacement
AI is increasingly being cited in US layoff announcements, with nearly 5% mentioning it in 2025. But these appear to be concentrated in the technology sector, which intuitively makes sense given the capex ramp-up in recent years.
As a share of real GDP, hardware and software investment has climbed by 1.7% points over the past 5 years.

Explicitly attributed AI layoffs are concentrated in the technology sector
It is also notable that payroll employment for the sector peaked just after ChatGPT was launched. But factors unrelated to AI are also likely to have played a part. Over-hiring during the pandemic may be partially to blame, while the higher interest rate environment since the pandemic has been a significant headwind to the sector.
Shrinking tech payrolls has not held back the sector
Whatever the reason, the 5% fall in technology employment from its peak accounts for only a fraction of the US jobs slowdown. Last year, the industry shed 75,000 jobs. Compare that to hiring in the rest of the economy, which was just 600,000 in 2025, or almost a tenth of the 5.5 million created in in 2022.
Tech layoffs account for a fraction of US jobs slowdown
While we have established that AI has not led to a significant number of layoffs, it could still be weighing on job creation more broadly across the US economy. But a bottom-up analysis of occupational exposure to AI suggests there has been little difference between jobs more at risk of being automated than those less at risk since 2022.
Jobs vulnerable to AI appear largely unaffected
Another popular argument is that firms are no longer hiring entry-level roles because AI can perform many junior tasks. Yet measures of youth unemployment have not seen a structural departure from the prime age unemployment rate, suggesting that AI is not impacting labour demand at the margin.
AI doesn’t appear to be crowding out young workers
The slowdown in job creation globally can instead be more convincingly explained by a combination of non-AI factors. Tariff uncertainty is likely to have dampened labour demand across almost every economy. This is coupled with country‑specific headwinds, which could include increases in the minimum wage and employer National Insurance Contributions in the UK; and rising competitive pressures from China’s automotive industry for the likes of Germany.
Chinese car exports now exceed Germany’s and Japan’s combined
In the US, tighter immigration policies have also weighed on job creation. Research from the Federal Reserve (Fed) shows that the slowdown in employment gains since 2022 largely reflects lower labour supply rather than demand. Should hiring intentions pick-up whilst supply stays constrained, wage pressures could intensify as a result.
US jobs slowdown largely reflects lower labour supply
At face value, this implies inflation risks remain skewed to the upside. But the presumptive Fed Chair Kevin Warsh believes the US is in the midst of an AI productivity boom, implying scope for lower rates. Our dissection of labour trends since 2022 suggests that this boom has yet to arrive. Cutting rates now would therefore amount to a bet on an unproven technology, all whilst models imply policy is already accommodative.
Models imply fed funds rate is at or below neutral
If US policymakers ease prematurely on the expectation of AI‑induced disinflation, they risk re‑igniting price pressures. The yield curve could steepen as a result as rally at the front end rubs up against a selloff in longer maturities, whilst breakevens also could climb higher as inflation becomes embedded.
Breakevens could climb higher if FOMC continues to cut
For professional investors and advisers only. The material is not suitable for retail clients. We define “Professional Investors” as those who have the appropriate expertise and knowledge e.g. asset managers, distributors and financial intermediaries.
Investment involves risk.
This information is a marketing communication. The information contained herein is believed to be reliable. Where third-party data is referenced, it remains subject to the rights of the respective provider and must not be reproduced or used without prior consent.
Any data has been sourced by us and is provided without any warranties of any kind. It should be independently verified before further publication or use. Third party data is owned or licenced by the data provider and may not be reproduced, extracted or used for any other purpose without the data provider’s consent. Neither we, nor the data provider, will have any liability in connection with the third party data.
The material is not intended to provide, and should not be relied on for accounting, legal or tax advice, or investment recommendations. Reliance should not be placed on any views or information in the material when taking individual investment and/or strategic decisions.
Any references to securities, sectors, regions and/or countries are for illustrative purposes only.
Past performance is not a guide to future performance and may not be repeated. The value of investments and the income from them may go down as well as up and investors may not get back the amounts originally invested. Exchange rate changes may cause the value of any investments to rise or fall. Schroders has expressed its own views and opinions in this document, and these may change.
This document may contain “forward-looking” information, such as forecasts or projections. Any forecasts stated in this document are not guaranteed and are provided for information purposes only.
Schroders will be a data controller in respect of your personal data. For information on how Schroders might process your personal data, please view our Privacy Policy available at https://www.schroders.com/en-za/za/intermediary/footer/privacy-policy/ or on request should you not have access to this webpage.
For your security, communications may be recorded or monitored.
Issued in March 2026 by Schroders Investment Management Ltd registration number: 01893220 (Incorporated in England and Wales) which is authorised and regulated in the UK by the Financial Conduct Authority and an authorised financial services provider in South Africa FSP No: 48998.
Schroders plc
Schroders is a global investment manager which provides active asset management, wealth management and investment solutions, with £823.7 billion (€943.4 billion; $1107.9 billion) of assets under management at 31 December 2025. As a UK listed FTSE100 company, Schroders has a market capitalisation of circa £6.5 billion and operates across 38 locations. Established in 1804, Schroders remains true to its roots as a family-founded business. The Principal Shareholder Group continues to be a significant shareholder, holding approximately 44% of the issued share capital.
Schroders’ success can be attributed to its diversified business model, spanning different asset classes, client types and geographies. The company offers innovative products and solutions through four core business divisions: Public Markets, Solutions, Wealth Management, and Schroders Capital, which focuses on private markets, including private equity, renewable infrastructure investing, private debt & credit alternatives, and real estate.
Schroders aims to provide excellent investment performance to clients through active management. This means directing capital towards resilient businesses with sustainable business models, consistently with the investment goals of its clients. Schroders serves a diverse client base that includes pension schemes, insurance companies, sovereign wealth funds, endowments, foundations, high net worth individuals, family offices, as well as end clients through partnerships with distributors, financial advisers, and online platforms.
Issued by Schroder Investment Management Limited. Registration No 1893220 England. Authorised and regulated by the Financial Conduct Authority. For regular updates by e-mail please register online at www.schroders.com for our alerting service.
