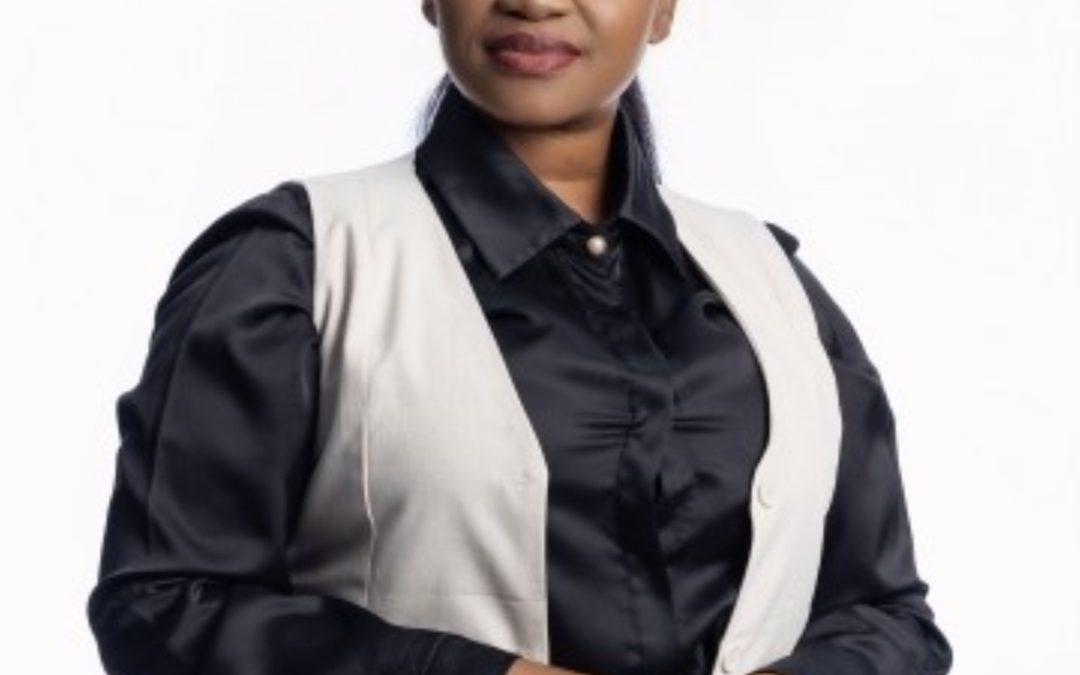
Salem Nyati, Consumer Financial Education Specialist at Momentum Group, is pointing out the dangers South African couples face when they share debt. She warns that when partners take out personal loans for each other or sign for loans together, it often leads to one person being left with no money and heavy debt if the relationship ends.
“Despite good intentions, taking on debt for someone else can quickly place you under financial strain and compromise your ability to support your own household,” she explains. “The emotional toll of a breakup is already significant – financial consequences shouldn’t add to that burden.”
The real cost of love through loans
According to TransUnion’s Consumer Credit Index Report for H1 2025, South Africa’s household debt is 62.7% of disposable income, with nearly 1 million consumer accounts in arrears. Against this backdrop, Nyati cautions that when people with substantial personal debt take on additional obligations for romantic partners, they risk their financial stability and family security.
The scenario plays out in several ways, she adds suggesting that a partner might take out a personal loan, with their significant other co-signing as security. Alternatively, one partner might guarantee a credit facility, apply for a joint loan, or allow their name to be added to an existing credit agreement. In each case, the person taking on this obligation becomes legally liable for the full debt, regardless of what happens in the relationship.
When relationships dissolve, the legal obligations remain unchanged. The debt does not disappear simply because love has left the building. Instead, it becomes what Nyati refers to as “loan debris”, the financial wreckage left behind when romance ends.
“People often do not realise they have agreed to something that will follow them indefinitely,” she says. “If your partner defaults on a loan you have co-signed or guaranteed, creditors will recover the money from you. A default will damage your credit record and may compromise your ability to secure finance for your own priorities; securing a home, education or unexpected emergencies.”
A burden beyond heartbreak
The consequences are far-reaching, Nyati believes. When one party is held responsible for a debt they did not control, they must choose between two impossible positions. They can either pay debt on behalf of someone who has moved on with their life, or they can default and watch their credit rating crumble.
A damaged credit record affects employment opportunities, insurance premiums, access to housing and future borrowing capacity. For those trying to support children or parents, taking on unmanageable debt for a partner can mean that money is no longer available for essential household needs.
“Your primary financial obligation is to your own household and dependents,” she emphasises. “When you commit to debt for someone else, you are potentially compromising your ability to meet those obligations.”
Education over emotion
What makes this situation particularly concerning is that many people do not understand the legal implications of co-signing an agreement or the long-term consequences of guaranteeing debt. They may not know that their credit record will be affected, that they can be taken to court, or that this debt could follow them for years after a relationship ends.
Nyati stresses that financial education is the remedy to this problem. People need to understand their rights, their obligations, and their vulnerabilities before they sign anything. They need to know that kindness is not the same as financial responsibility and that love does not override legal contracts.
“Education empowers people to make informed choices,” she says. “If someone chooses to support a partner financially, that is their decision. But they should do so with a full understanding of what they’re agreeing to and what the worst-case scenario could look like.
Ask yourself difficult questions
For those already caught in this situation, the path forward requires honest conversations and potentially professional guidance. Those considering taking on debt for a partner should pause and ask themselves difficult questions. What happens if the relationship ends? Can I afford this debt on my own? What will the impact be on my family and my future?
There are alternatives to co-signing. Partners can apply for loans individually. They can make smaller financial contributions without legal obligations. They can set boundaries that protect their own financial wellbeing whilst still showing support.
“Relationships are built on trust and communication,” Nyati concludes. “That trust and communication should extend to money. Partners deserve to know whether their significant other is willing to take on debt for them, and what the real costs might be.”